A Beginner's Guide to Investing (Part 16): RRSP vs. TFSA for Middle-Income Canadians
Why a TFSA May Be a Better Choice for Middle-Income Canadians — Even When an RRSP Offers an Immediate Tax Break
In Part 15, we compared RRSP and TFSA investing options for low-income Canadians and concluded that, in most cases, a TFSA is the better choice. In this article, we will examine which option generally makes more sense for middle-income Canadians.
What is the Middle-Income Range?
There is no single official definition of “middle class” or “middle-income range” in Canada. One practical way to think about it is to look at median individual incomes by age, which reflect what a typical person earns.
According to Statistics Canada’s Canadian Income Survey, 2024 (Income of individuals by age group):
- The median total income (before tax) for individuals aged 25–54 is $58,500.
- The median total income (before tax) for individuals aged 35–44 is $63,800.
- The median total income (before tax) for individuals aged 45–54 is $65,800.
For this article, we will use an annual employment income of $70,000 as an illustrative example. This is somewhat higher than the median individual income for Canadians in their prime working years. We will examine whether investing in an RRSP or a TFSA makes more sense over the long term.
Story of Two Savers
Assume Bob and Raj are both 25 years old, live in Ontario, and earn an annual employment income of $70,000 each.
Based on 2026 tax rates, an individual earning $70,000 in Ontario would pay approximately $11,134 in income tax and contribute $5,080 towards CPP and EI premiums. This leaves an after-tax income of approximately $53,786.
Bob, the RRSP Saver
Bob, an RRSP saver, decides to contribute $9,000 to his RRSP. Since RRSP contributions are tax-deductible, this reduces his taxable income and results in estimated tax savings of approximately $2,669.
Note: Employers generally deduct income tax at source based on the employee’s regular payroll information. An employee can submit Form T1213 (Request to Reduce Tax Deductions at Source). Unless the employer adjusts tax deductions to account for Bob’s RRSP contribution, Bob would receive the resulting tax refund when he files his 2026 income tax return.
The following table summarizes the tax comparison:
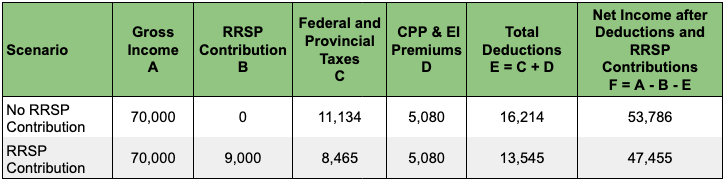
Bob’s $9,000 RRSP contribution reduces his estimated income tax from $11,134 to $8,465, resulting in tax savings of approximately $2,669. This represents an immediate tax saving of approximately 29.65% of his RRSP contribution.
In other words, although Bob contributes $9,000 to his RRSP, his net cost is only $6,331 after accounting for the estimated tax savings ($9,000 − $2,669).
Raj, the TFSA Saver
Now, let’s consider Raj, who earns the same annual income as Bob but chooses to invest in a TFSA instead.
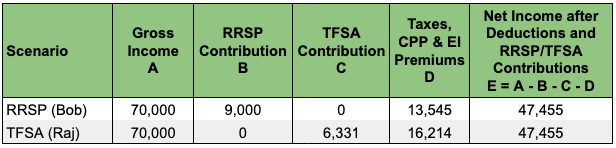
To make the comparison fair, assume Raj contributes $6,331 to his TFSA using after-tax income. Unlike Bob, Raj does not receive a tax deduction or refund for his contribution.
Thus, both Bob and Raj invest the same amount of their disposable income ($6,331), but Bob invests $9,000 in his RRSP while Raj invests $6,331 in his TFSA. The net disposable income in both cases is the same.
The following table summarizes their respective situations:
The Accumulation Phase: Investing for 40 Years
Now, let us assume that Bob and Raj continue investing for the next 40 years, until they reach age 65 and retire. Bob continues contributing $9,000 annually to his RRSP, while Raj contributes $6,331 annually to his TFSA. Both increase their annual contributions in line with inflation, keeping their contributions equivalent to these amounts in today’s dollars.
We will also assume that both invest in diversified equity portfolios and earn an average annual real rate of return of 5% (i.e., after adjusting for inflation).
Note: A 5% real return is a reasonable assumption for this illustrative example, considering the historical long-term returns of broad equity markets. Actual investment returns, of course, will vary from year to year and may be higher or lower.
Based on these assumptions, the accumulated investment values after 40 years, expressed in today’s dollars, would be approximately:
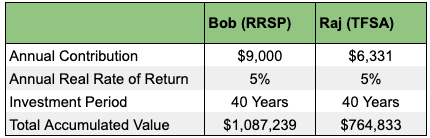
As you can see, Bob accumulates approximately $1,087,000 in his RRSP, compared with Raj’s $765,000 in his TFSA.
However, these figures do not tell the whole story. Bob’s RRSP withdrawals will be taxable, whereas Raj can withdraw his TFSA savings tax-free.
If Bob’s effective tax rate on his RRSP withdrawals is approximately 29.65%, his after-tax RRSP savings would be roughly equivalent to Raj’s TFSA savings. However, if Bob can withdraw his RRSP savings at a lower effective tax rate than the tax rate at which he received the original RRSP deduction, his RRSP strategy would leave him better off. Conversely, if his effective withdrawal tax rate is higher, the TFSA would provide a better outcome.
Therefore, to determine which saver is better off, we need to compare their investments after accounting for the taxes payable on RRSP withdrawals during retirement. We should also consider how those withdrawals may affect income-tested government benefits, such as OAS and GIS, where applicable.
The Retirement Journey
Bob and Raj have retired at age 65.
During their working years, Bob and Raj each had $47,455 remaining after accounting for income tax, CPP/EI contributions and their respective annual savings contributions. Assume that they need $3,900 per month ($46,800 annually) in after-tax income during retirement.
For this example, assume that Bob and Raj are each entitled to a CPP retirement pension of approximately $1,945 per month ($23,340 annually), expressed in today’s purchasing power. This CPP payment represents approximately 33.33% of their $70,000 employment income during their working years.
Note: The estimated CPP pension of $1,945 per month used in this example assumes 40 years of contributions under the fully enhanced CPP system, which has been fully phased in since January 1, 2025. Individuals retiring in the next few years will receive considerably less because they will not have accumulated 40 years of enhanced CPP contributions. For 2026, the maximum and average monthly CPP retirement pensions at age 65 are $1,507.65 and $858.34, respectively.
Since they have both lived in Canada for at least 40 years after turning 18, they would qualify for the full Old Age Security (OAS) pension, which is $762.50 per month ($9,150 annually) as of November 2026.
Their annual income from government benefits would therefore be:
- CPP: $23,340
- OAS: $9,150
- Total: $32,490
Since their required annual retirement income is $46,800, their government benefits fall short of their retirement income target by $14,310, before accounting for income tax.
Both Bob and Raj have accumulated sufficient savings in their RRSP and TFSA, respectively, to cover this shortfall.
Bob’s RRSP Withdrawals
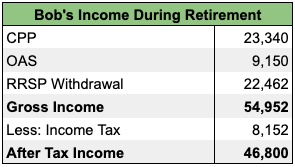
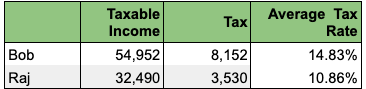
CPP, OAS and RRSP withdrawals are 100% taxable income. Based on 2026 Ontario tax rates for seniors, Bob needs to withdraw approximately $22,462 from his RRSP, bringing his total gross income to $54,952. This income will attract approximately $8,152 in income tax, leaving him with $46,800 in after-tax income.
With an assumed annual real return of 5%, Bob’s RRSP balance of approximately $1,087,000 would increase in value by about $54,350 during the first year, before withdrawals. Therefore, an annual withdrawal of approximately $22,458 would allow the account balance to continue growing under these assumptions. (Of course, actual investment returns will fluctuate.)
Here are Bob’s income sources to generate $46,800 in annual income:
Note: Bob could potentially reduce his income tax by converting a portion of his RRSP into a Registered Retirement Income Fund (RRIF) and withdrawing $2,000 annually from the RRIF. Since Bob is over 65, eligible RRIF withdrawals qualify for the pension income tax credit, whereas ordinary RRSP withdrawals do not. This credit would reduce his tax payable and, consequently, the total amount he needs to withdraw from his RRSP.
Raj’s TFSA Withdrawals
Unlike RRSP withdrawals, all TFSA withdrawals are 100% tax-free. Raj’s income from CPP and OAS payments is $32,490. Raj needs to withdraw enough money to pay tax on $32,490, plus additional money to bring his after-tax income to $46,800. Income tax for a senior on $32,490 in annual income is $3,531; therefore, Raj needs to withdraw $19,640 from his TFSA.
Here are Raj’s income sources to generate $46,800 in annual income:
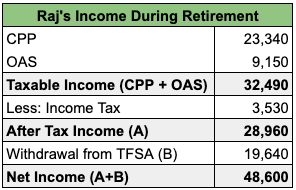
Raj’s TFSA account balance of approximately $765,000 at age 65, earning an assumed 5% real return, would generate about $38,250 in annual growth before withdrawals. Therefore, an annual withdrawal of approximately $19,640 would allow his TFSA balance to continue growing under these assumptions. Of course, actual investment returns will fluctuate.
Notice that Raj pays significantly less tax in retirement as compared to Bob. Whereas Bob paid a tax of $8,152, Raj paid only $3,530, though both have the same after-tax income.
TFSA Flexibility vs. RRIF’s Strict Withdrawal Rules
A TFSA offers complete flexibility: Raj can increase, decrease or stop withdrawals whenever he needs to. An RRSP, however, must be converted into a RRIF, used to purchase an annuity, or otherwise dealt with by the end of the year Bob turns 71.
Most people transfer their RRSP savings into a Registered Retirement Income Fund (RRIF). Although investments can continue growing on a tax-deferred basis inside a RRIF, there is one important difference: a RRIF requires a minimum amount to be withdrawn every year.
The minimum withdrawal is not based on what Bob needs — it is calculated using a government-prescribed percentage of the RRIF’s value on January 1 of each year, based on his age. The percentage increases as he gets older. For example, the minimum withdrawal factor is 5.28% at age 71, 5.40% at age 72, 6.82% at age 80, 8.51% at age 85, 11.92% at age 90 and 20% at age 95 or older.
Bob’s RRIF after Age 71
Bob’s RRSP account value at age 65 is approximately $1,087,000. As stated earlier, at a 5% real annual rate of return (after inflation), the account generates more growth than Bob’s annual withdrawal of $22,458. Thus, the account value will continue to increase over the next 6 years, and it will have an approximate value of $1,300,000.
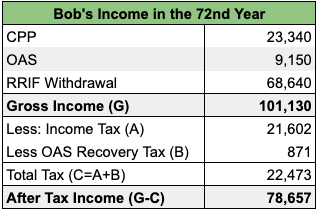
If Bob establishes his RRIF at age 71, his first mandatory minimum withdrawal will be in the following calendar year. Since Bob will still be 71 on January 1 of that year, the applicable minimum withdrawal factor will be 5.28%. Assuming the RRIF is worth $1,300,000 on January 1, his minimum withdrawal would be approximately $68,640. This entire withdrawal is taxable as income. The withdrawal will bring Bob’s annual income to $101,130. This will not only result in higher income tax, but it will also trigger the OAS recovery tax, commonly known as OAS Clawback.
Here is Bob’s income and tax summary in his 72nd year.
OAS Clawback (Recovery Tax)
As defined by the Government of Canada, if your net world income exceeds a specific annual threshold, you must repay part or all of your Old Age Security pension. This is officially known as an “OAS pension recovery tax.”
For 2026, the OAS recovery tax threshold is $95,323. For every dollar of net income above this threshold, 15 cents of OAS is recovered, up to the maximum OAS pension received.
Since Bob’s net income is $101,130, his income exceeds the threshold by $5,807. His OAS recovery tax is therefore approximately $871 ($5,807 × 15%).
In the seventh year of retirement, Bob’s income tax and OAS recovery tax total $22,473, compared with $8,152 each during the first six years of retirement. His after-tax income also increases to $78,657, substantially more than his annual retirement income target of $46,800.
In contrast, Raj has no mandatory withdrawal requirement from his TFSA. Because his CPP and OAS are his only taxable income sources, he still pays about $3,531 in annual income tax while withdrawing what he needs from his TFSA.
Bob Loses Age Amount Credit
Another reason Bob pays significantly higher taxes is that he loses most of the available Age Amount Credit. This non-refundable tax credit is available to Canadian residents who are 65 years of age or older.
The federal and Ontario age amount credits are gradually reduced when net income exceeds their respective thresholds. The reduction is 15 cents for every dollar of net income above the applicable threshold.
For 2026, the federal age amount begins to decrease when net income exceeds $46,432, while the Ontario age amount begins to decrease above $47,210. At Bob’s net income of $101,130, his Ontario age amount is completely eliminated, while only a small portion of his federal age amount remains.
Bob’s Tax Will Keep Rising
As the mandatory minimum withdrawal from an RRIF is based on the account balance at the beginning of each year and the government-prescribed factor for Bob’s age, his required withdrawals will generally increase as he gets older.
Although Bob is withdrawing money from his RRIF, the assumed 5% annual real investment return almost offsets these withdrawals. Consequently, the account balance declines only gradually.
At a 5% assumed annual real rate of return, Bob’s minimum RRIF withdrawal will increase to approximately $70,000 at age 72 (in the 73rd year), $71,400 at age 73, $72,800 at age 74, and $74,250 at age 75.
These increasing withdrawals will add to Bob’s taxable income, resulting in higher income tax, a potentially larger OAS recovery tax, and a further reduction in his Age Amount Credit.
In contrast, Raj can decide how much to withdraw from his TFSA. Even if he increases his TFSA withdrawals, those withdrawals will not increase his taxable income or affect his OAS pension.
Raj’s TFSA Keeps Rising
Raj’s TFSA balance at age 65 is approximately $765,000. At an assumed real annual rate of return of 5%, his investments generate approximately $38,250 in growth during the year. Since he withdraws only $19,640 annually, his TFSA balance increases by approximately $18,610, reaching $783,610 at the beginning of the following year.
As the account balance grows, the dollar amount of investment growth also increases. Since Raj’s annual withdrawal remains unchanged at $19,640, his TFSA balance will continue to grow as he ages.
Assuming a consistent 5% real annual return and withdrawals at the end of each year, his TFSA balance will be approximately $891,000 at age 70, $1,029,000 at age 75, $1,205,000 at age 80 and $1,430,000 at age 85.
The best part is that TFSA withdrawals are tax-free at any age. The value of Raj’s TFSA at the time of his death can also pass to his beneficiaries without being included in his taxable income.
RRIF Tax Liability at Death
Another potential disadvantage of having a large RRIF balance is the tax liability when the account holder dies.
Despite making substantial withdrawals from his RRIF each year, Bob’s account value does not decrease significantly. Assuming a consistent 5% real annual rate of return and minimum withdrawals at the end of each year, his RRIF balance will be approximately $1,265,000 at age 75, $1,180,000 at age 80 and $1,026,000 at age 85.
If Bob dies while holding a substantial RRIF balance, the general rule is that the fair market value of the entire RRIF immediately before his death is included in his income on his final tax return. This could result in a significant tax bill, particularly if the RRIF balance pushes much of his income into higher tax brackets.
Note: If Bob’s spouse is named as the successor annuitant, the RRIF can generally continue in the spouse’s name without triggering immediate tax. A qualifying transfer to a surviving spouse may also receive tax-deferred treatment. However, this only defers the tax liability; it does not eliminate it.
What can Bob do to increase his Estate Value?
Although Bob cannot avoid the mandatory minimum RRIF withdrawals, he can take steps to manage his taxable income and potentially improve the after-tax value of his estate. Here are three strategies worth considering:
- Withdraw more from his RRSP between ages 65 and 71: Although this will result in higher income tax during these years, it will reduce the RRSP balance transferred to his RRIF and may therefore lower future mandatory withdrawals. This could help reduce OAS recovery tax and the loss of age amount credits in later years.
- Save the surplus income generated by mandatory RRIF withdrawals: From age 71 onward, Bob’s after-tax income may exceed his annual spending needs because of the mandatory RRIF withdrawals. Rather than spending this surplus, he can contribute to his TFSA, subject to available contribution room, or invest it in a non-registered account. If he has a spouse or common-law partner, he can also gift money to them so they can contribute to their own TFSA, provided they have sufficient contribution room.
- Split RRIF Income and Share CPP with Spouse: If Bob has a spouse or common-law partner with lower income, he may be able to allocate up to 50% of his eligible RRIF income to them for tax purposes. He and his spouse may also apply to share their CPP retirement pensions, subject to the applicable CPP rules. These arrangements can help reduce Bob’s individual taxable income, potentially lowering his income tax, OAS recovery tax and the reduction of his Age Amount Credit.
For more details, see my articles on Registered Retirement Income Fund (RRIF) and CPP Explained in Plain English.
Employer RRSP Matching: Don’t Leave Free Money Behind
Our RRSP vs. TFSA discussion so far has generally favoured the TFSA for middle-income Canadians. However, there is one important exception: always take advantage of an employer RRSP match, especially if the employer matches your contributions 100%.
For example, if you contribute $5,000 and your employer matches it with another $5,000, you immediately have $10,000 invested in your RRSP. This is an effective 100% return on your own contribution before investment growth. The money can then continue to grow on a tax-deferred basis inside the RRSP.
An employer match can make an RRSP more attractive than a TFSA, even for someone earning $70,000 annually. However, consider the plan’s vesting requirements, investment fees and withdrawal rules, as well as the potential impact of future RRSP/RRIF withdrawals on taxable income and income-tested benefits such as OAS.
For more details, see the following articles:
Conclusion: TFSA or RRSP — Which One Should You Choose?
Our comparison of Bob and Raj demonstrates that choosing between an RRSP and a TFSA involves more than simply looking at the immediate tax savings.
At an annual employment income of $70,000, Bob receives an immediate tax saving of approximately 29.65% on his RRSP contribution. However, his RRSP withdrawals in retirement are taxable. As his RRSP balance grows, the mandatory minimum withdrawals from his RRIF increase his taxable income, trigger OAS recovery tax and reduce or eliminate age-related tax credits.
Raj, on the other hand, does not receive an immediate tax deduction for his TFSA contributions. However, his investments grow tax-free, and he can withdraw as much or as little as he needs without increasing his taxable income. He also avoids mandatory withdrawal requirements and can potentially leave a substantial tax-free inheritance to his beneficiaries.
For many Canadians earning around $70,000 annually, these advantages can make the TFSA a more attractive retirement savings option than the RRSP.
That does not mean an RRSP should be ignored. If your employer offers RRSP matching, take full advantage of it. An employer match can provide an immediate and substantial benefit. An RRSP may also be more attractive if you receive a tax deduction at a higher rate during your working years and expect to withdraw the money at a lower effective tax rate in retirement.
The bottom line: For many middle-income Canadians, prioritizing the TFSA can provide greater flexibility and tax advantages in retirement. However, take advantage of any employer RRSP matching first, and consider your current and expected retirement tax rates before deciding how to divide your remaining savings between an RRSP and a TFSA.
Check out other articles in this series: A Beginner’s Guide to Investing
Disclaimer: This article is for educational purposes only and is not financial or tax advice. Please consult a qualified tax or financial professional before making any decisions.
What are your thoughts on this post? Share your comments with us.
Stay ahead of the curve. Subscribe here to get notified whenever I publish a new guide or tool.
Share your comment or feedback. We'll get back to you as soon as we can.