A Beginner's Guide to Investing (Part 12): Time in the Market vs. Timing the Market
Why Staying Invested Beats Trying to Time the Stock Market
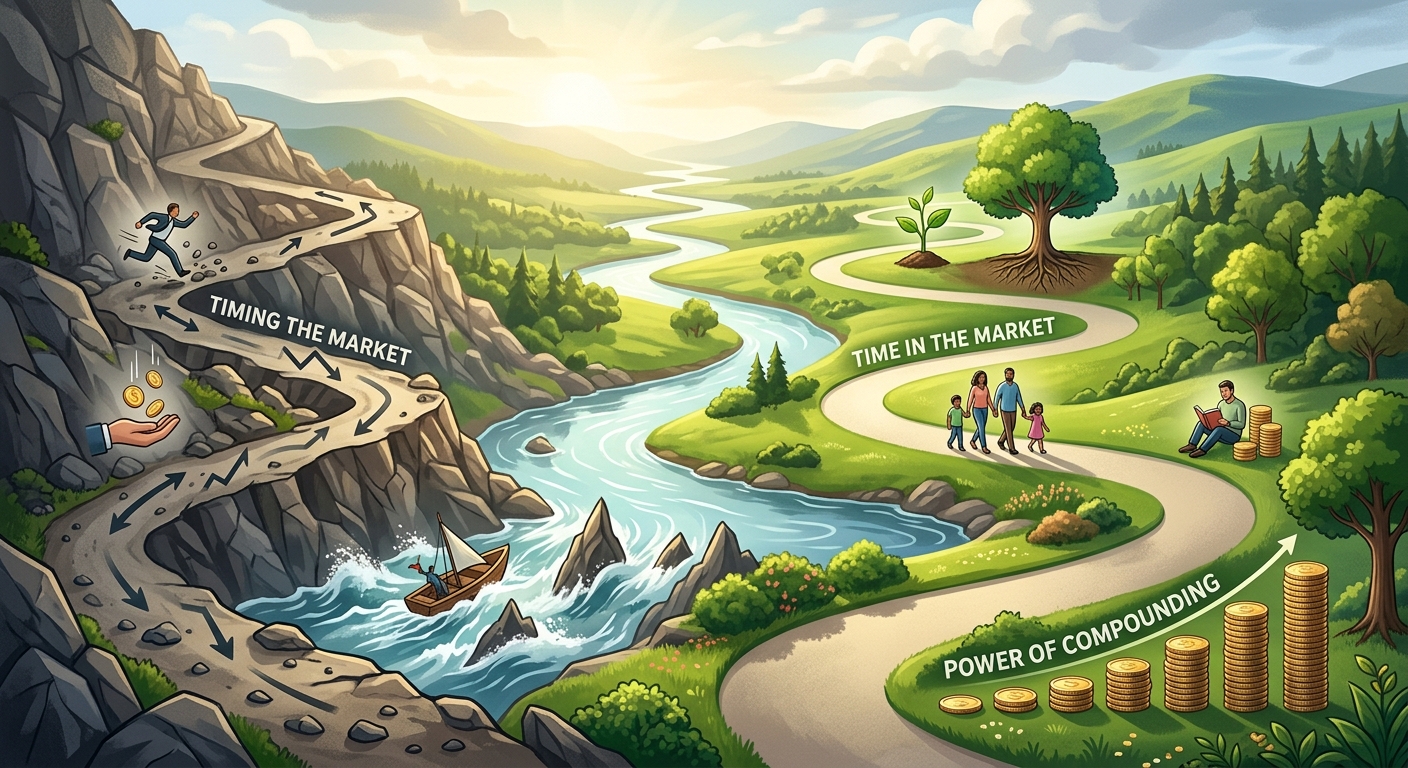
After people start investing in the stock market, gain some experience and see their investment portfolio grow, they sometimes become impatient.
How can I make big money in the stock market in a short time?
Some investors feel that if they can buy a stock when its price is low and sell it after it rises 20%, 30%, or even 50% in a few months, they can make a lot of money quickly.
At first glance, it seems to make sense. If you buy a share for $100 and sell it for $130, you have made a 30% return. It would be great if you could do this in a short period — say, two or three months.
And if you could repeat this successfully several times a year, your money could grow very quickly. For example, three consecutive 30% gains would turn $100 into about $220, a gain of about 120%.
Many stocks do gain 30% or more in a few months. The challenge is knowing which stocks will rise, when they will rise, and when to sell.
Trying to make investment decisions based on predicting short-term market movements is called “timing the market.”
The Problem with Timing the Market
While the “timing the market” approach may seem like a quick and easy way to make money, there are many problems with this strategy.
First, you have to identify when a stock or the stock market is low.
This may seem easy in the internet era, when you have access to information about almost everything. However, remember that everyone else has access to much of the same information. Some investors may also be much more experienced and knowledgeable than you.
There are two sides to every market transaction. For every buy order, there is a corresponding sell order. If you think a stock is undervalued and decide to buy it, someone else is willing to sell it at that price. That seller may believe the stock is already fairly valued — or even overvalued — and therefore thinks it is a good time to sell.
Who is right? You won’t know until later.
The important point is that you cannot assume that your assessment of the stock’s value is better than the assessment of the person on the other side of the trade. You may be right, but you may also be wrong.
When to Sell a Stock
The next part of the “timing the market” approach is deciding when to sell a stock after its price rises. Let us assume that you are lucky and the stock you bought starts rising soon after you purchase it. But when should you sell it — after it increases by 10%, 20%, 30% or 50%?
While the downside of a stock is limited — a stock priced at $20 can fall to zero — the upside potential is theoretically unlimited. That $20 stock could rise to $40, $100 or even $500 over the years.
What if you sell a stock you bought at $20 for $30 after six months, making a 50% gain, but the stock continues to rise over the next several years? By selling too early, you have given up the opportunity to participate in a much larger gain.
And what if the stock you bought because you believed it was undervalued keeps falling? Will you have the courage to sell the stock at a loss and look for another opportunity, or will you continue holding it, hoping that it will eventually recover?
From my experience, I have found that many new investors find it psychologically difficult to sell a stock at a loss when they originally bought it expecting a large profit. They may hold on simply because they don’t want to admit their original decision was wrong, while the stock keeps falling.
BCE and TELUS, two well-known Canadian companies that have traditionally been popular with investors, provide a recent example of how painful this can be. From around 2021 to September 2026, their share prices have fallen by more than 50%. An investor who bought either stock near its 2021 level and continued holding it would have seen a substantial decline in the value of the investment. For an investor who bought these stocks at much higher prices, it can be difficult to decide whether to accept the loss and move on or continue holding the stocks in the hope that they will eventually recover.
There is another important issue. After you sell a stock, you have to identify another investment and decide when to get back into the market. While you are holding cash and looking for another opportunity, the stock market may continue to rise, and you may miss part of that gain.
You may be surprised to learn that a significant portion of the stock market’s long-term gains can occur during a relatively small number of trading days. If you are out of the market during some of those strong days, missing those gains can have a significant impact on your long-term returns. (See: No One Has a Crystal Ball, Yet Often People Act as Though They Do)
Tax Consequences of Frequent Buying and Selling
Though some online brokerages offer zero-commission trades, others still charge a commission on each trade. Frequent buying and selling can therefore create transaction costs that reduce your investment returns.
There can also be tax consequences. If you buy and sell stocks in a non-registered (taxable) account, you have to report your capital gains and losses on your tax return. When you sell a stock for a profit, the resulting capital gain is taxable.
Frequent trading can therefore make your tax situation more complicated and can result in taxes becoming payable sooner than if you simply held your investments for the long term.
Time in the Market
So far, we have looked at some of the problems with trying to time the market. You have to decide when to buy, when to sell, when to cut your losses, and when to get back into the market. Getting all of these decisions right consistently is extremely difficult. There is a simpler approach:
Stay invested and give your investments time to grow.
This is often referred to as “time in the market.” Instead of trying to predict short-term movements in stock prices, you invest with a longer-term perspective and remain invested through the market’s ups and downs.
The stock market will inevitably experience periods of decline, sometimes significant ones. If you are investing for the long term and your investments remain fundamentally sound, a temporary decline does not necessarily mean that you should sell. By remaining invested, you continue to participate when the market eventually recovers and rises again.
In fact, as you gain experience and go through a few market declines and recoveries, you may become more comfortable with these ups and downs. The first significant decline in your portfolio can be unsettling, but after experiencing a few cycles, you may start to see market declines as a normal part of investing rather than something to fear. This can make it easier to stay focused on your long-term investment plan instead of reacting to short-term market movements.
The Power of Compounding
Another important benefit of staying invested is compounding.
Compounding means that your investment can earn returns not only on the money you originally invested, but also on the returns that have accumulated over time.
For example, suppose you invest $10,000, and your investment earns an average return of 8% per year.
Year 1: Your investment earns 8% of $10,000, which is $800. Your investment is now worth $10,800.
Year 2: The 8% return is now calculated on $10,800, not just the original $10,000. You earn $864, bringing your investment to $11,664.
Year 3: The 8% return is now calculated on $11,664. You earn about $933, bringing your investment to about $12,597.
Notice what is happening: the $800 you earned in the first year is now part of your investment and is also earning a return. This is the basic idea behind compounding.
If the investment continues to earn an average of 8% per year, the $10,000 would grow to about $21,589 after 10 years and about $46,610 after 20 years, assuming no money was added or withdrawn.
Note: An 8% average return is only an illustration. Actual investment returns vary from year to year, and some years can produce negative returns.
The point is that the longer your money remains invested, the more time your returns have to compound.
You Don’t Have to Predict the Market
A big advantage of staying invested is that you don’t have to predict what will happen in the market next week, next month, next quarter or next year.
Suppose the market falls 20% and an investor sells their investments because they expect the market to fall further. However, they now have to make another decision: When should I buy back in?
If the market recovers suddenly while they remain on the sidelines, they miss the market upside.
In other words, when an investor tries to time the market, they need to make two timing decisions: when to sell and when to buy again, and both have to be right.
On the other hand, an investor who remains invested does not face this problem. Their portfolio may decline temporarily during a downturn, but they are already invested when the recovery begins.
Note: Staying invested does not mean that you should blindly hold every investment forever. Individual stocks may decline when the underlying business deteriorates, and there can be good reasons to sell an investment. The idea behind “time in the market” is not “never sell” — it is to avoid making investment decisions simply because you are trying to predict short-term market movements. However, if you invest in a broad-based ETF that holds thousands of companies across different countries and industries, there may be much less reason to sell simply because the price of the ETF has declined. You can remain invested and allow the ETF to participate in the eventual recovery of the market.
Time in the Market vs. Timing the Market
The difference can be summarized as:
Timing the market: When should I buy? When should I sell? When should I get back in?
Time in the market: I have a long-term investment plan. I will stay invested and give my investments time to grow.
For a long-term investor, the second approach can be much simpler. Instead of trying to predict market movements, you focus on choosing appropriate investments, diversifying your portfolio, and giving your investments time to compound.
You cannot control what the stock market will do tomorrow. But you can control how you invest, how long you remain invested, and whether you allow short-term market movements to change your long-term plan.
Check out other articles in this series: A Beginner’s Guide to Investing
Disclaimer: This article is for educational purposes only and is not financial or tax advice. Please consult a qualified tax or financial professional before making any decisions.
What are your thoughts on this post? Share your comments with us.
Stay ahead of the curve. Subscribe here to get notified whenever I publish a new guide or tool.
Share your comment or feedback. We'll get back to you as soon as we can.